
Artificial intelligence needs far more than chips and code. It needs vast, hungry data centers that run around the clock, and Microsoft’s disclosure of over US$130b in new data center leases shows how intense that buildout has become. Power suppliers linked to this surge now sit closer to the action than many investors realise, which can create both opportunity and risk. This article breaks down 3 stocks exposed to that story and explains how each could fit, or fail to fit, in a data center driven portfolio.
The three utilities in the spotlight here are only a teaser, as the wider screen surfaced 47 more listed grid and power operators with equally compelling data center narratives that this article does not cover. To see how they line up for your own watchlist, head straight into the Electric Utilities and Grid Operators Supplying Hyperscale Data Centers screener to identify, analyze, and prioritize the highest conviction ideas for your portfolio.
Elia Group sits right on the high voltage highways that feed Europe’s hyperscale and AI data centers, which is why it screens so strongly here and why its investment plan has drawn so much attention.
Execution of a record CapEx pipeline through 2028 in both Belgium and Germany, backed by a strengthened balance sheet and EUR 11.9 billion of available liquidity, is intended to steadily expand the regulatory asset base and support higher regulated revenue and earnings.
What happens to Elia Group’s earnings profile if a single pressure point in that build program or its regulation shifts even slightly?
Elia Group operates high voltage transmission grids in Belgium and Germany that are central to powering large data centers. Most revenue comes from Elia Transmission at €1.7b and 50Hertz Transmission at €3.1b, with international activities at €86 million. The stock’s market cap is about €13.1b.
That earnings question sits at the center of the Elia Group story, and the full narrative for Elia Group shows how regulation, grid buildout, and data center demand could all be pulling in different directions.
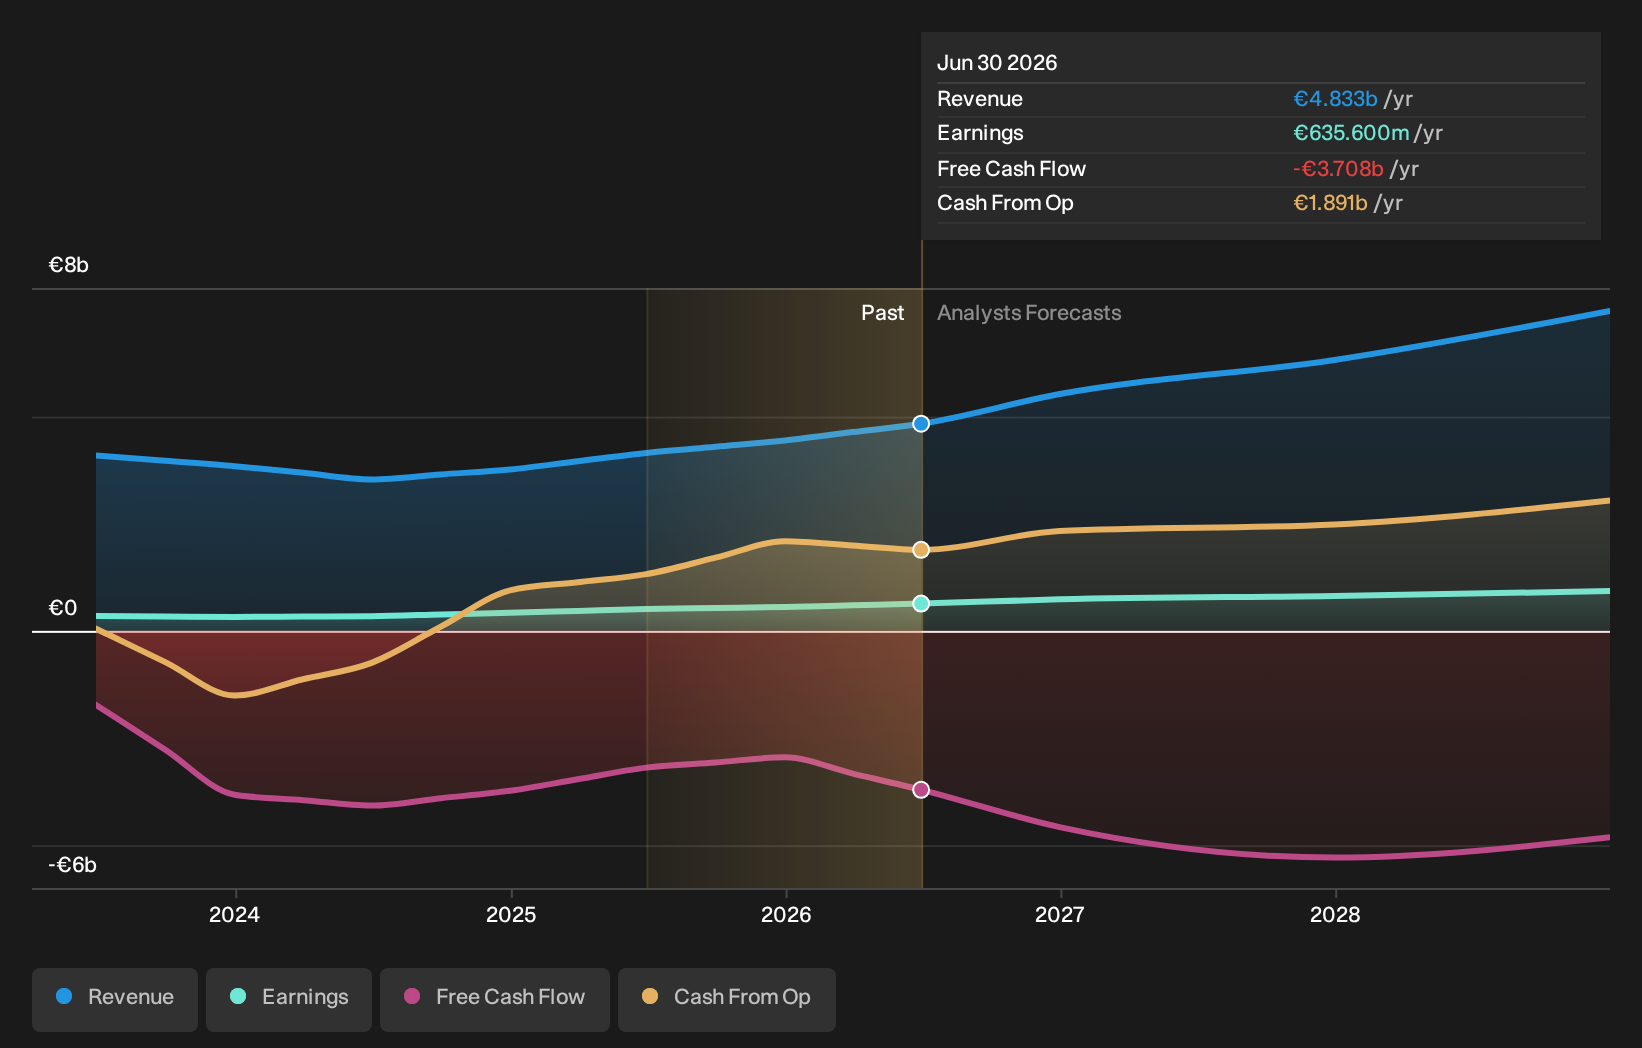 ENXTBR:ELI Earnings & Revenue Growth as at Oct 2026 National Grid (LSE:NG.)
National Grid is one of the key gatekeepers for hyperscale and AI data centers in the UK and US Northeast, because it owns and operates the high voltage networks and substations those facilities must plug into, turning future electricity demand into long-lived, regulated assets.
National Grid runs electricity and gas transmission and distribution networks in the UK and US Northeast, closely tied to large data center power connections. Most revenue comes from New York at £7.6b and New England at £4.2b, with UK Electricity Transmission at £2.9b and UK Electricity Distribution at £1.9b. The group, including National Grid Ventures and other activities, has a market value of about £58.5b.
That role as a grid landlord for AI infrastructure is why Microsoft’s lease surge matters for National Grid, because more hyperscale power demand usually means more regulated steel in the ground for this utility.
National Grid plans to invest around £60 billion in its networks over the next 5 years. This is expected to drive significant asset growth and provide strong visibility on future revenues.
What investors still need to judge is how much of that planned build can translate into durable returns if a single regulatory lever shifts against it.
When that regulatory dial moves, the full narrative for National Grid shows where National Grid’s returns could accelerate, stall, or quietly decouple from headline investment numbers.
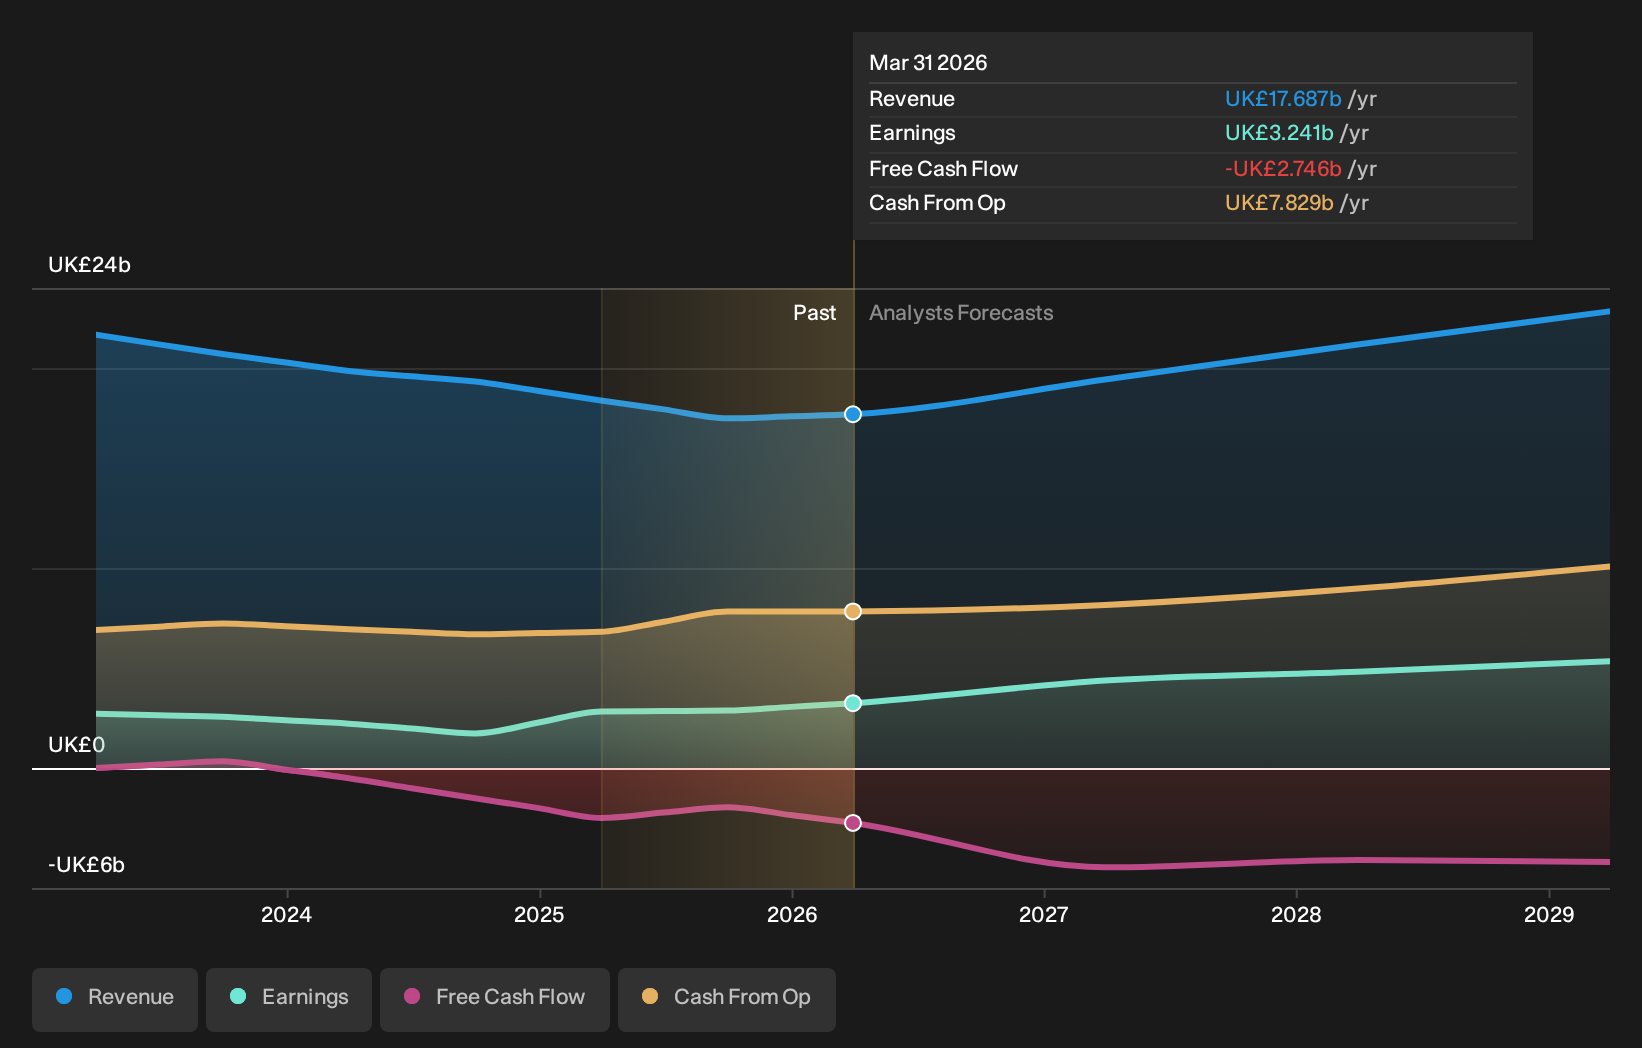 LSE:NG. Earnings & Revenue Growth as at Oct 2026 Redeia Corporación (BME:RED)
Redeia Corporación runs Spain’s high voltage grid that hyperscale data centers ultimately depend on, operating around 46,074 kilometers of transmission lines. Most revenue comes from domestic electricity infrastructure at about €1.5b, with €77 million from international grids and €144 million from fiber optics. The group’s market value is roughly €8.1b.
Redeia Corporación controls Spain’s only high voltage backbone, so every large AI or cloud data center that wants power must deal with this grid operator. However, investors still have to think carefully about what happens if a single key assumption in its regulated returns shifts.
If that assumption moves even slightly, the 1 key reward and 2 important warning signs (1 is major!) shows where Redeia Corporación’s regulated grid story could quietly accelerate or stall.
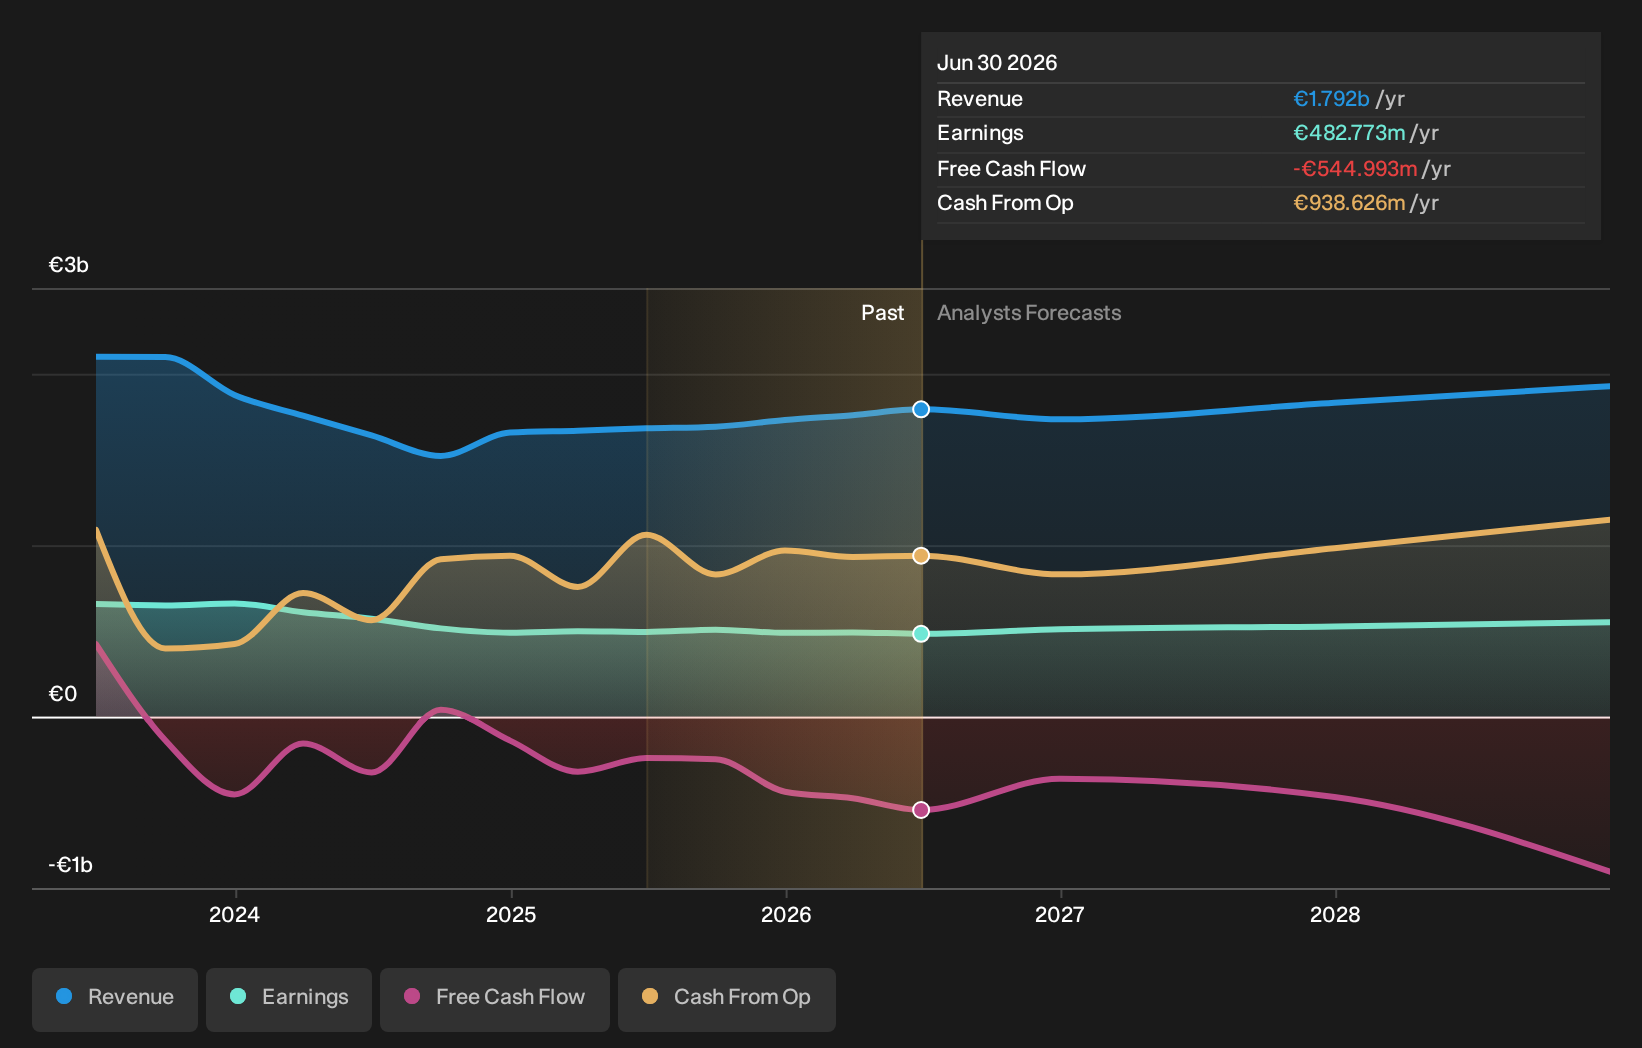 BME:RED Earnings & Revenue Growth as at Oct 2026 Seeking Alternatives Before Momentum Flies
Fresh opportunities move fast. Breakout stories get caught early, momentum builds, and prices can be flying before the crowd reacts. Check these ideas while it matters and consider them promptly.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if National Grid might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com