
Australian inflation recently reached 4% as housing and transport costs pushed interest rates to a 15 year high. Higher borrowing costs make capital intensive projects harder to finance, which puts efficient rare earth producers in the spotlight. Investors looking for exposure to the clean energy and advanced technology supply chain are watching this niche closely. This article highlights three rare earth miners from our Australian screener worth closer attention.
The three stocks highlighted below are just a small sample of the rare earth miners on the radar, and the full screen surfaced 13 more Australian and global companies with equally compelling narratives that are not covered here. To size up that wider field quickly, head straight to the Rare Earth Metal Stocks screener to identify, compare, and analyze rare earth metal stocks aligned with your highest conviction ideas.
Overview: Minerals 260 is an Australian explorer focused on gold and base metals, with rare earth elements targeted at its Moora project.
Market Cap: A$1.99b
Minerals 260 provides early stage exposure to rare earth elements through its Moora ground in Western Australia, while recent funding and royalty deals around its Bullabulling Gold Project indicate that the balance sheet can support sustained exploration. The key question is how future drilling outcomes at Moora may interact with any expectations already priced into this rare earth story.
To see how much of that optimism is already priced in, go to the DCF valuation analysis for Minerals 260 and gauge where expectations may be stretching ahead of Moora.
 MI6 Discounted Cash Flow as at Oct 2026 Arafura Rare Earths (ASX:ARU)
Overview: Arafura Rare Earths is developing the Nolans rare earths deposit in Australia to supply NdPr and other oxides for high-tech, EV and defense supply chains.
Market Cap: A$1.06b
Arafura Rare Earths matters for this rare earths screen because the Nolans project is designed to move from ore to separated oxides, plugging directly into magnet and clean energy value chains that want options outside China.
“Growing electric vehicle adoption and the push for diversified magnet supply chains outside China are supporting long-term NdPr demand, which could help Arafura Rare Earths secure pricing that supports revenue and cash flow visibility over future contract periods.”
What ultimately happens to Arafura Rare Earths margins and cash generation will hinge on how one critical assumption in those future contracts holds up.
If that contract assumption is the real swing factor, the full narrative for Arafura Rare Earths explains how Arafura Rare Earths risk, financing and offtake dynamics could be decoupling.
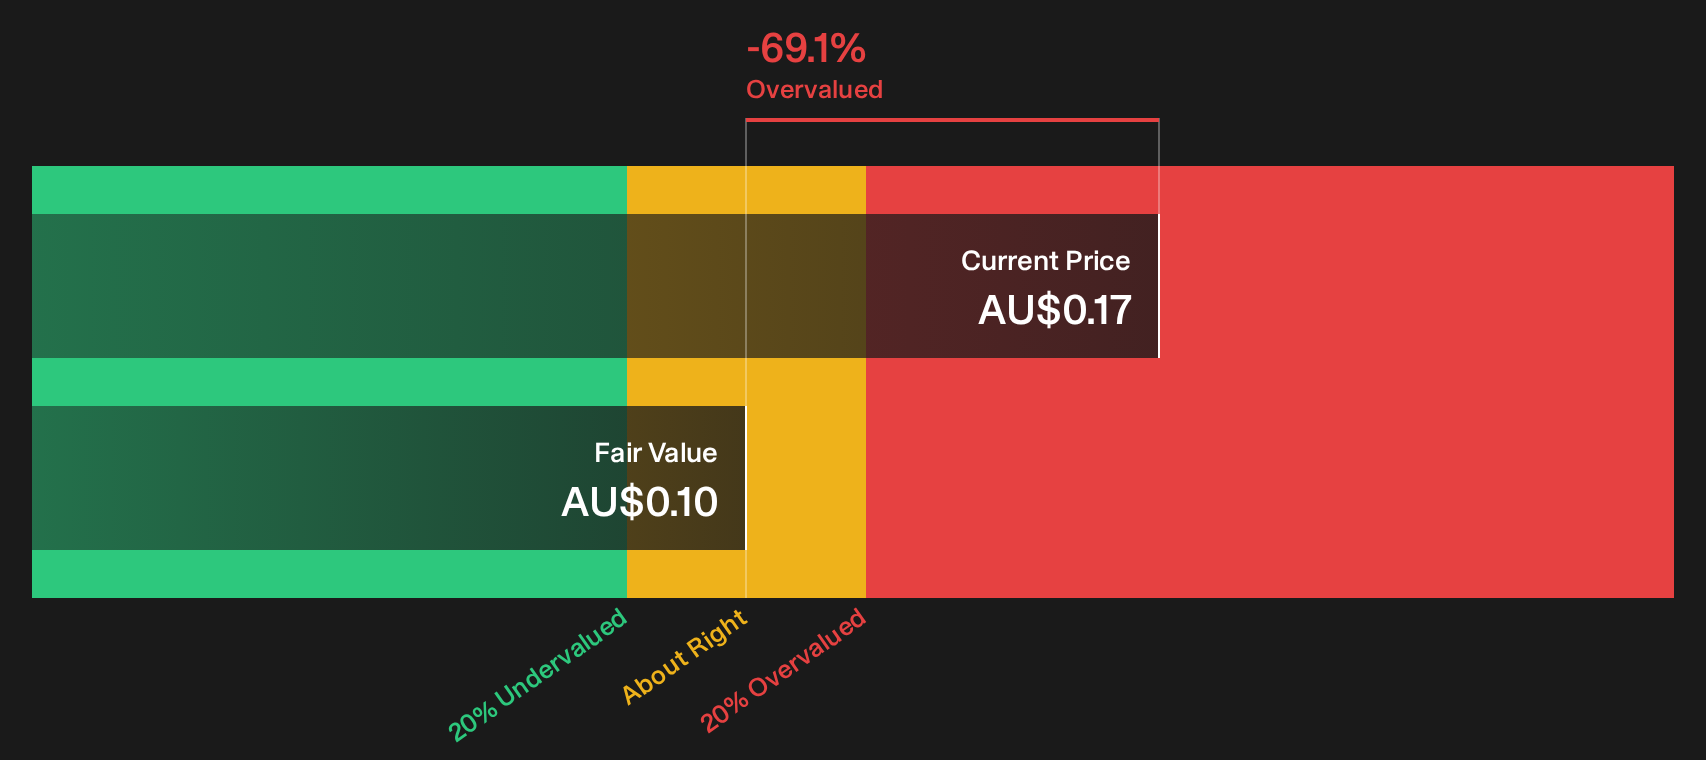 ARU Discounted Cash Flow as at Oct 2026 Lynas Rare Earths (ASX:LYC)
Overview: Lynas Rare Earths runs the Mt Weld mine in Australia and processing plants in Australia and Malaysia to produce key rare earth materials for EVs, wind turbines, and defense technologies.
Operations: Lynas Rare Earths currently earns about A$978 million in revenue from its Rare Earth Operations segment, tightly linked to critical mineral demand.
Market Cap: A$13.9b
For investors focused on secure access to critical minerals, Lynas Rare Earths offers one of the clearest pure plays on rare earth supply from outside China, which is why expectations around its future contracts and policy support attract so much attention.
“Investors appear to expect sustained above-trend pricing and demand, largely based on the belief that Western governments’ ongoing support for supply chain diversification and critical mineral security will continue to provide Lynas with long-term government-backed offtake agreements and pricing floors, which in turn would support higher future revenue and valuation multiples.”
What happens to Lynas Rare Earths margins if that single policy-driven support pillar weakens or shifts even slightly will be crucial.
If that policy support does start to shift, the full narrative for Lynas Rare Earths explains how Lynas Rare Earths cash flows, contracts and valuation risk could be quietly decoupling.
 LYC Discounted Cash Flow as at Oct 2026 Seeking Alternatives Before The Crowd
Fresh ideas often move first. Some gain momentum quietly, then move higher before most investors even notice. Scan these under the radar for now opportunities while it matters and consider them early in your research process.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com